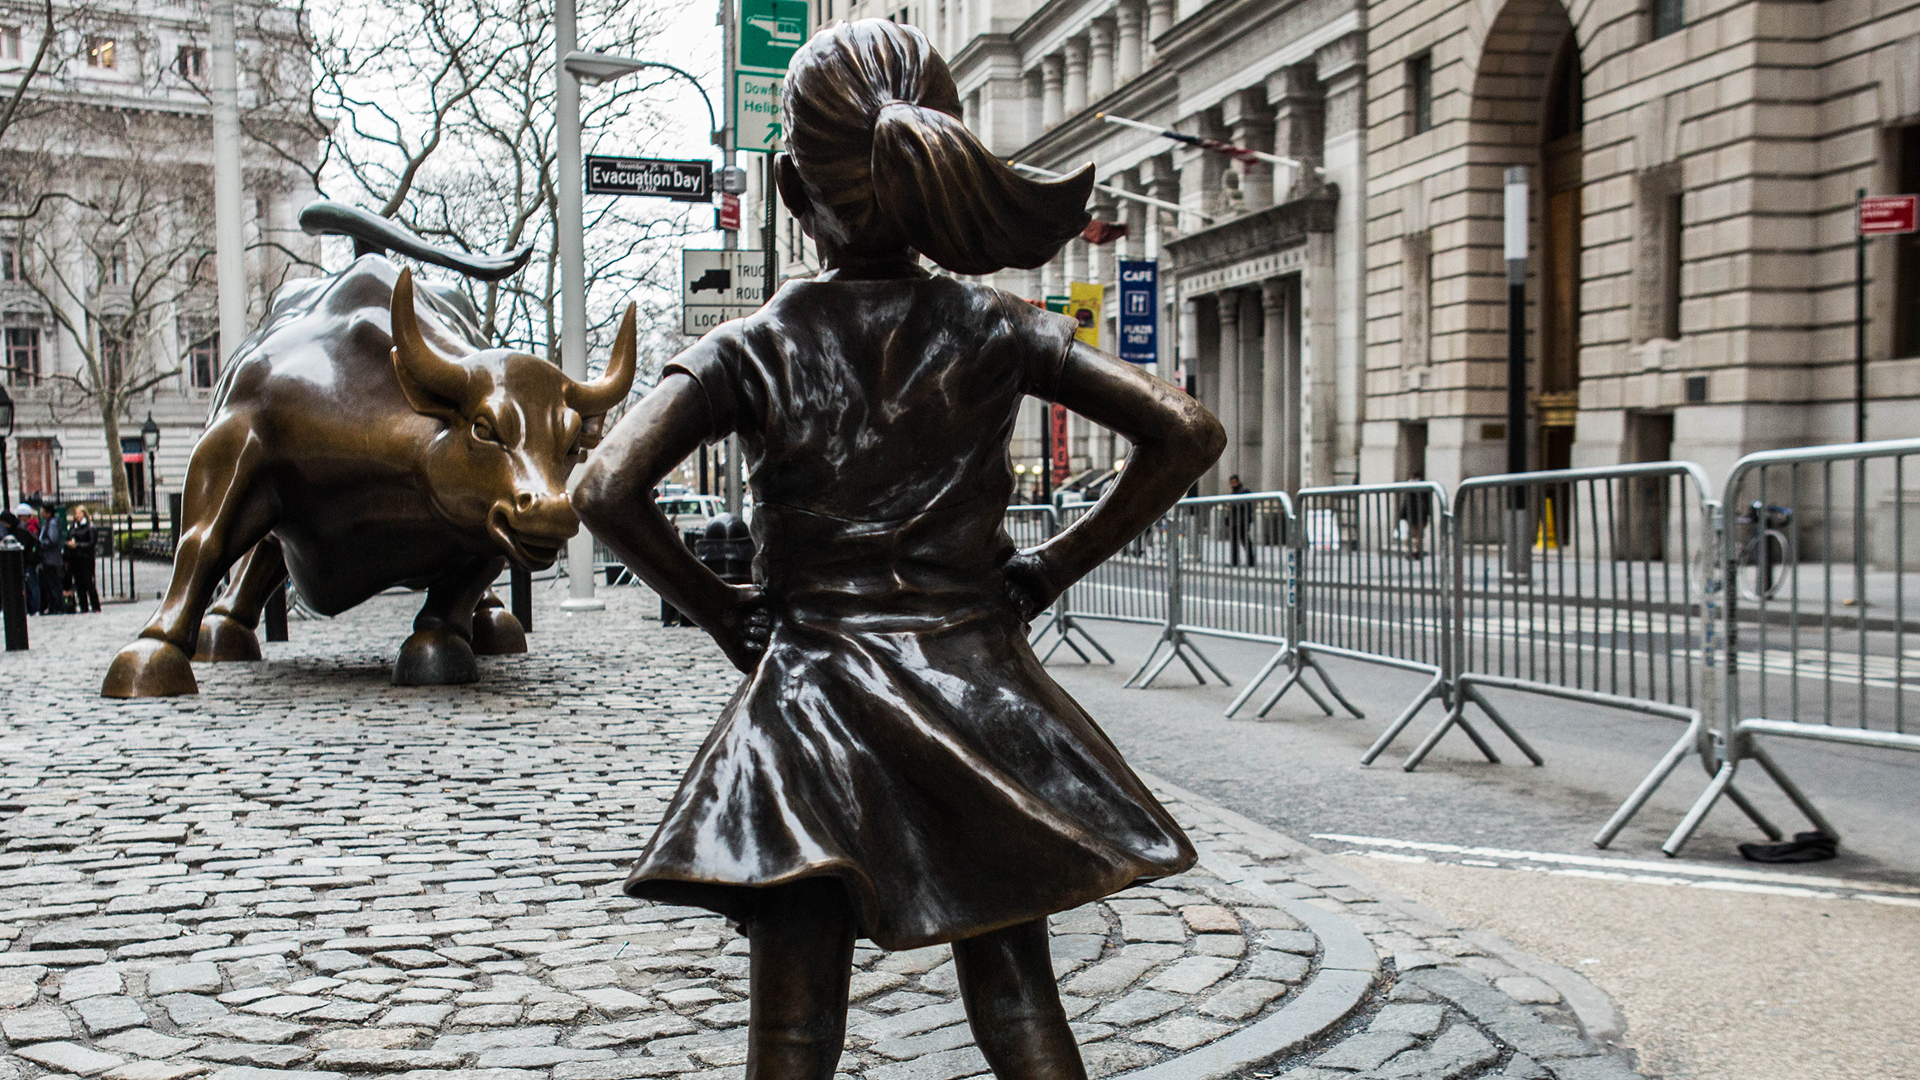
It was 1933, the depths of the Great Depression. Businesses were collapsing and millions were out of work, not just in the United States of America but around the world.
That year, a struggling newspaper went under the hammer in America’s capital. The winning bid had been placed anonymously.
The next morning, 16-year-old Katharine picked up the newspaper to read the headline:
EUGENE MEYER ANNOUNCED AS WASHINGTON POST BUYER.
She was as surprised as anyone else in Washington, D.C. The buyer was her father.
Soon Katharine enrolled at Vassar College, a prestigious women’s liberal arts college nestled in a vast leafy campus in New York’s Hudson Valley. After graduating, she worked as a reporter at the San Francisco News before returning to Washington and joining The Washington Post.
By then, her father had spent years rebuilding the paper. But when Meyer thought about succession, none of his four daughters were in the running. In fact, when a 21-year-old Katharine ran the “Letters to the Editor” 1 department in 1938, he said, “If it doesn’t work, we’ll get rid of her.”
Over the next two decades2, Meyer transformed the loss-making paper into a profitable and influential local media business. In 1946, Meyer, an accidental media baron who had previously served as governor of the Federal Reserve Board, prepared to head the newly created World Bank. His only son, whom Meyer had hoped to hand the baton to, wasn’t interested in the top job.
So, Meyer propped Katharine’s husband, Philip Graham, a Harvard Law School graduate, as The Post’s publisher. He even gave Philip more voting stock than Katharine, who had by then taken her husband’s last name to become Katharine Graham. His explanation was unmistakably patriarchal: “I thought a man should not work for his wife.”
Katharine Graham had settled into a life of raising four children and hosting dinners for politicians, journalists and diplomats. Then, in 1963, Philip killed himself, leaving 46-year-old Katharine wondering whether to sell the newspaper or run it herself. At that point, she had not been regularly employed for nearly 20 years.
When she decided to run the newspaper herself, many Post executives scoffed at the idea. As a corporate rookie, Graham too was intimidated by this male-dominated world. So, she leaned on people she trusted and let them do their jobs.
Eight years passed and on June 15, 1971, The Washington Post Company made the leap from a privately-held family business to a company listed on the New York Stock Exchange. The champagne had barely gone flat when Graham found herself at a crossroads.
Good Fortune
More than half a century ago, Katharine Graham took over The Washington Post, reluctantly stepping into a role few women held at the time. In the decades since, progress has been slow. Women still expect to inherit less wealth than men.
That gap shows up in both the U.S.3 and India4. About 28% of women, compared with 32% of men in the U.S., and close to 10% of women, compared with 14% of men in India, said they had received or expected to receive an inheritance from their parents.
The difference may seem small. But if women don’t expect the money to come, they may not be equipped to compound their wealth when they receive it.
A lot of wealth is about to change hands. In the U.S. alone, an estimated USD 84.4 trillion5 is expected to pass to the next generation, much of it through women as they tend to live longer than men. In India, women are expected to inherit at least INR 73 trillion6 over the coming decade.
That makes the question of confidence tougher to ignore. In the U.S., only 9%7of women said they expected to outperform men as investors. Another data point for India8, showed about 50% of women made their investment decisions independently, compared with approximately 70% of men.
For much of the twentieth century, in most households, husbands were the principal earners and often the ones who opened and operated the brokerage account. Male members of the family flipped through salmon-pink business newspapers, watched the stock ticker and thumped the table over what to buy. Women didn’t have a chance to get their hands greasy.
Moreover, investing became word salad of alpha, beta, asset allocation and diversification. It seemed like a hard-to-crack, encrypted code.
“Dear Doris and Bertie”
Legendary investor Warren Buffett recognized this problem early. Beginning in the mid-1970s, he wrote his shareholder letters with his two younger sisters, Doris Buffett and Roberta “Bertie” Buffett, in mind.
“I start off mentally writing, ‘Dear Doris and Bertie,’” Buffett once said9 “And then I just cross them off and put, ‘To the shareholders of Berkshire Hathaway.’”
Those letters are now part of investing folklore. Buffett wrote for ordinary shareholders—people who needed to understand how they could earn a decent return.
In his 2004 shareholder letter10, Buffett explained how a good company can make money for years, and still some shareholders may never profit exponentially from it.
“Investors should remember that excitement and expenses are their enemies,” Buffett wrote.
What he meant was that investing often works best when you do less. Buy a good business at a sensible price, keep costs low, and give it time. That was the essence of compounding as your returns start earning returns of their own. The longer you leave the investment alone, the more powerful that process becomes.
Buffett had been putting that idea to work for years. One of his most famous investments began with a company we have already met: a newspaper company, run by a woman who was thrust into leadership.
When Buffett was 14, shortly after his family moved to D.C., he cycled swiftly through Northwest Washington as a newspaper boy11, flinging tightly rolled copies of The Washington Post onto front porches. Decades later, he was buying its shares.
It was 1973, just two years after The Washington Post Company went public. Buffett believed the market was valuing its profitable newspaper and television businesses at a fraction of what they were truly worth. So, he put USD 10.6 million12 into it.
Four decades later, Berkshire’s remaining stake was exchanged for assets then worth about USD 1.16 billion13, in addition to decades of dividends. By 2013, those dividends alone were bringing in about USD 17 million14 a year, more than Buffett had originally paid for the investment.
While Buffett was looking for value in 1973, he was struck by Graham’s willingness to learn and think long term. He took her through annual reports to make her understand financial statements. Graham was not embarrassed by what she did not know, and she learned.
Buffett came to admire Graham’s patience, a quality that may be more familiar to women than the investing world gives them credit for.
Women have historically traded less15 than men and that restraint pays off. A 10-year U.S. analysis found that women earned, on average, 0.4 percentage points more than men, annually. The number sounds tiny. Over decades, however, even a small difference in annual returns can compound into a meaningful sum.
Researchers in the UK found something similar. While men earned an annual return 0.14% above the FTSE 100, Britain’s main stock-market index, the women beat the index by 1.94%16. They made about 9 trades a year, compared with 13 for men. Men were more likely to believe they could outsmart17 the market. As a result, they traded more often and made worse bets.
Slow and Steady
Of course, women also panic. They chase trending stocks and wager bad bets, just as men do. But, on average, women may keep their fists a little tighter around cash.
They are more likely to think about money in terms of what it can protect18 and preserve over the long term. Women also take a cautious stance during economic slumps with cutbacks19 on non-essential spending and plans to save more.
Andrew Ross Sorkin is the author of 1929: Inside the Greatest Crash in Wall Street History—and How It Shattered a Nation. He spent nearly a decade digging for stories on the people and decisions behind the stock market panic that triggered the Great Depression.
In a recent interview20 with talk-show host Oprah Winfrey, Andrew was asked: Would the world have been better off in 1929 if women had had a greater say in decision-making?
“Most of the people who were in charge were men,” he said. “But I would argue that a couple of women around the table, or maybe a lot of women around the table, might have helped.”
His point was that women might be less likely to follow the crowd when everyone else is buying frantically, or feel they always need to be doing something. That matters most after, when markets fall.
Increasingly, there is another reason to take control of that decision for women.
Globally, women tend to live longer than men. In the U.S.21, life expectancy is about 81 years for women, compared with 76 for men. In India22, it is roughly 73 years for women versus 69 for men. Those extra years must be paid for.
So, women face a peculiar financial problem. Not only are they increasingly likely to control the wealth, but they also need that wealth to last longer.
All That Glitters
In F24, India’s female labor-force participation rate for women aged 15 and above rose to close to 42%23 from about 23% in F18.
But what were women doing with the money they earned?
For now, much of it is still parked somewhere safe. A survey24 of women earners across Indian cities found that 51% of their investments were in fixed deposits and savings accounts. Gold accounted for another 16%, mutual funds 15%, real estate 10% and direct stock ownership just 7%.
For Indian women, gold is not merely jewelry that’s passed from mother to daughter, it is a rainy-day umbrella. The shiny metal is pledged for a loan when cash is needed. When prices rise or financial markets are in trouble, gold can sometimes hold its value or even rise when other things are falling.
Still, its long-term performance pales in comparison to stocks. If you look at the period from September 2001 to September 2026, gold compounded at about 10.45% a year. Meanwhile, the Sensex, an index tracking 30 large companies listed on India’s stock exchanges, delivered 12.92% and the Nifty, which tracks 50 large companies, logged 12.76%25.
Moreover, unlike a business, gold doesn’t produce anything or generate cash while you own it. Warren Buffett made this distinction in Berkshire Hathaway’s 2011 shareholder letter26. He noted that an ounce of gold would always remain an ounce of gold. In contrast, a farm produces crops and a good business generates profits that it can reinvest to grow. Buffett’s preference was for these “productive assets.”
While women have spent generations learning to protect capital, it is now time to put it to work. And they are beginning to.
Women’s share of mutual-fund assets has been growing in India. Between December 2020 and December 2025, women’s slice of individual assets under management (AUM) more than tripled to INR 17.86 lakh crore27 from INR 5.44 lakh crore. That represents a 228% increase, compared with 187% for men.
And it is not just the amount of money women in India are investing that is changing, but also where they are putting it. Equity-focused funds28 rose to 65% of women’s mutual-fund assets by March 2025 from about 40% in March 2020.
And this is happening through Systematic Investment Plans (SIPs) which allow an investor to put a fixed sum into a mutual fund every month. The money earns returns; those returns remain invested and earn returns of their own.
This is particularly important as women often have an objective about what to do with the money. In a U.S. study29 on inheritance, many women planning to leave money to grandchildren described it as an expression of love and care. They also saw it as a way to create new opportunities and financial security.
And that purpose can extend beyond family.
A 2020 global survey found that 64%30 of women considered environmental, social and governance (ESG) reports while investing. This can mean considering how a company treats the environment and its workers, whether women participate in its leadership, or what sort of social impact the business creates. There’s an Indian business leader whose approach to wealth and leadership brings this idea to life.
Fearless Girl
Nisaba “Nisa” Godrej grew up31 in a family where money and business were not considered a man’s preserve. She had an older sister, Tanya, and a younger brother, Pirojsha. But from early on it was clear that the family business belonged to the daughters too.
Nisa has credited32 her grandmother, a schoolteacher, with raising her father to be an egalitarian and a feminist. Her great-grandmother was one of the first Indian women to attend university. And her mother, Parmeshwar Godrej, had the moxie to defy rules that shackled women.
When Nisa joined Godrej Consumer Products, she had inherited not just a surname and a shareholding but a sense of what it meant to have a place at the table as the Executive Chairperson of the company.
And she’s taken that very seriously. At Godrej, it has translated33 into flexible working, maternity support and programs that help women return after a career break. The company has also taken steps to make the workplace more welcoming to LGBTQ+ employees. She has also consciously included more women on the board34 at Godrej Consumer Products. All of this is in sync with her belief35, “You can do difficult things with love and decency.”
For generations, women were often taught to protect money rather than put it to work. Gold, fixed deposits and savings accounts offered safety. Conversations about business and investing happened in offices, clubs and, quite often, between fathers and sons.
Morgan Housel, the author of The Psychology of Money, believes that some of the most important lessons on finance are learned through the behavior of our parents and from conversations at the dinner table. It’s the kind of education Nisa had.
For a long time, women had fewer opportunities to pick up that knowledge informally. That is changing.
Women are now building their own financial circles36 through WhatsApp groups, workshops, online communities and informal gatherings. Financial literacy37 communities for women are growing. They are asking the questions beginners are supposed to ask. What exactly does a balance sheet tell me? What does this company actually do? What is a mutual fund?
For example, the term “balance sheet” may sound complicated but in reality, it is just a record of what a company owns, what it owes and what belongs to its shareholders. A mutual fund is simply a pool of money from many investors, invested in things such as shares or bonds.
Such conversations are more useful than a hot stock tip. The point is not to turn women investors into short-term stock traders but to enable them to find “excellent businesses run by excellent people at reasonable prices“38 and then allow those investments to compound over the long term.
Money is something to be put to work and that takes a little fearlessness.
In 2017, a 4-foot-tall bronze statue of an 8-year-old girl with her hands on her hips and chin raised appeared in New York’s Financial District. She stood opposite the giant Charging Bull39: a towering, three-decade-old metal installation, signaling rising markets.
The statue was called Fearless Girl. The temporary fixture was intended to symbolize the power and potential of women in leadership, in the male-dominated world of finance.
She now has a permanent Wall Street address outside the New York Stock Exchange.
Through The Looking Glass
Just 48 hours after The Washington Post Company went public, Katharine Graham learned that one of her editors had received a stash of classified documents.
The Pentagon Papers were a secret U.S. Defense Department study of the country’s involvement for nearly two decades in the Vietnam War40, which had begun in 1955.
What had started as American support for South Vietnam against the communist North had grown into a full-scale war, with the U.S. eventually sending more than 3 million troops to the Southeast Asian nation. By 1971, American soldiers were still dying in the conflict, while the government insisted that they were winning.
The Pentagon Papers told a different story. They showed that four successive presidents had misled the American public about the war and secretly deepened America’s involvement. They were doing this despite protests and growing signs of losing the war.
A military analyst41 who had worked on the study, turned whistleblower. He secretly copied the papers and gave them to The New York Times. Richard Nixon, the then U.S. president, tried to stop the papers from being published, invoking national security. A court order blocked The New York Times from publishing them.
The same source then gave part of the trove to The Washington Post.
On Thursday, June 17, 1971, the clock ticked away. Graham had to decide whether to print and put her company at risk or remain silent.
The government was already in court trying to stop the Times. Graham’s lawyers warned that publishing them could land the company in court and put its television licenses at risk.
Graham listened to the lawyers. Then she spoke to her editors and went ahead with the story. She did not know whether the Supreme Court would uphold the government’s attempt to stop publication or what the decision might cost the company. She only knew what she believed the newspaper had to do.
“I really hate fights but when cornered then I will fight,” Graham said42.
Two weeks later, the U.S. Supreme Court ruled that the newspapers could publish. The decision became one of the defining press victories of the era.
From the company’s IPO in 1971 until Graham stepped down as chairman in 1993, a dollar invested in The Washington Post Company grew to USD 89, compared with USD 5 in the S&P 500 and USD 14 among her peers. With a 22.3%43 annual return, Katharine Graham was by far the most successful newspaper executive of her time.
Years later, Warren Buffett, a major shareholder in the company, described the problem Graham had spent years confronting. The people around her had created44 what he called a “funhouse mirror,” stretching and shrinking her in different directions. She had begun to believe this image.
His role, he said, was to help turn that funhouse mirror into an ordinary one.
It’s time for women investors too to trust their judgment and sweep away distortions.